How to Organize Progress Photos and Invoices for Insurance Draws During a Fire Damage Rebuild
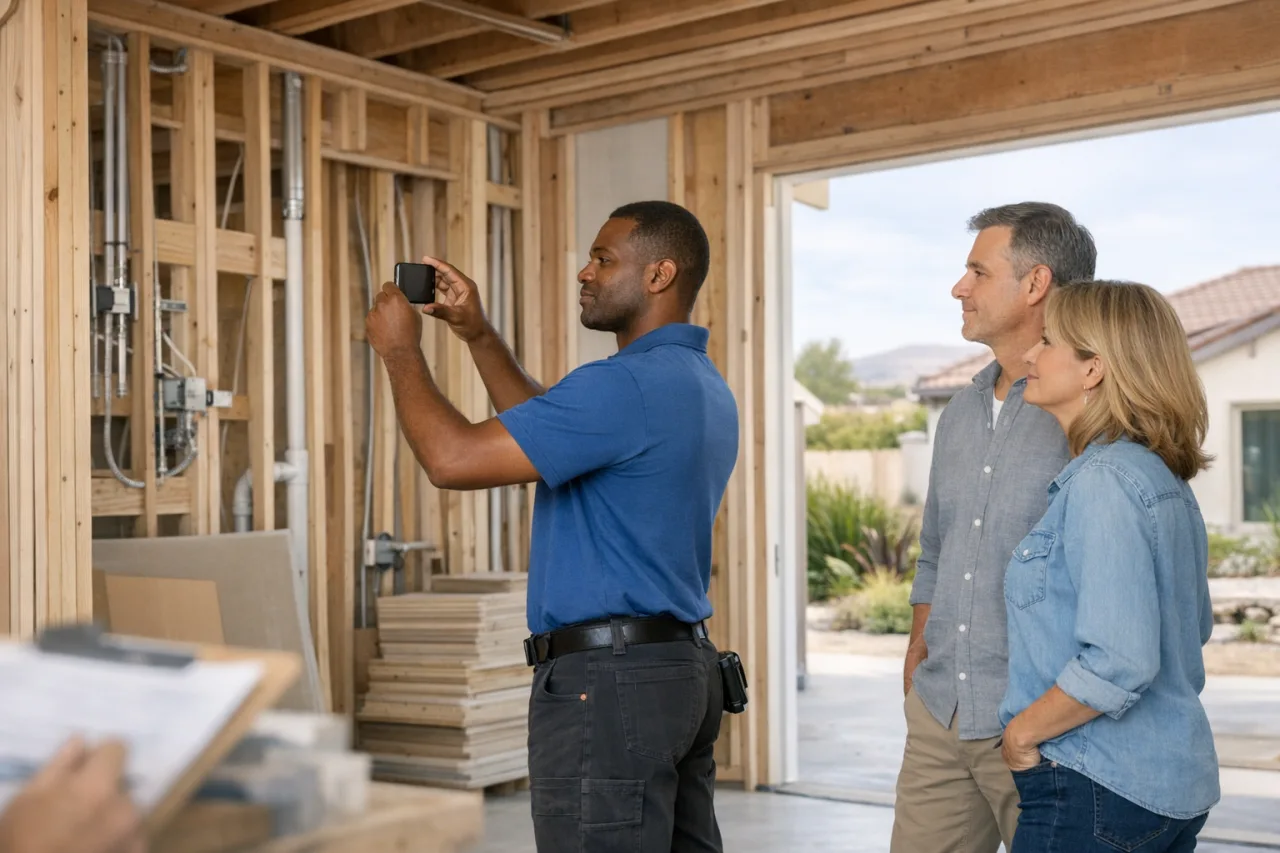
Progress photos and invoices for insurance draws should be organized by construction phase, matched to the adjuster's approved estimate line by line, and submitted together as a complete draw packet that includes a cover sheet, photo log, itemized invoices, proof of payment, and lien waivers. When documentation is structured this way, the insurance carrier or mortgage servicer's loss-draft department can review and release funds without unnecessary delays.
If you are a homeowner in Altadena or Pacific Palisades rebuilding after wildfire damage, the draw process will likely involve multiple rounds of documentation spanning many months. Your rebuild may include a dozen or more distinct construction phases, each requiring its own set of photos, invoices, and supporting records before the next portion of insurance funds is released. Managing that process involves coordination between you, your contractor, your insurance carrier, and — if you carry a mortgage — your lender's loss-draft department.
This guide walks through how to build a documentation system that keeps draws moving forward. It covers what an insurance draw actually is, how to structure your filing system, what photos and invoices to collect at each phase, how lien waivers work, how to assemble a draw packet, and what mistakes commonly cause delays.
What an Insurance Draw Is and Why Documentation Controls When Funds Are Released
An insurance draw is a partial payment released from your insurance claim proceeds to fund a specific phase of reconstruction work. Rather than issuing the full claim amount at the outset, insurance carriers typically release funds in stages as work is completed and verified. Each release requires a draw request supported by evidence that the work was actually performed, passed required inspections, and aligns with the approved scope of loss.
For homeowners carrying a mortgage, the process adds another layer of complexity. Your insurance check is often sent directly to the mortgage servicer, whose loss-draft department holds those funds and releases them in draws based on their own documentation review. The loss-draft department may dispatch a third-party inspector to confirm that the reported work is complete before authorizing any release.
This means documentation is not simply good practice — it is the mechanism that determines whether and when you receive funds. Incomplete or mismatched documentation is the most common reason draws are delayed, partially released, or flagged for additional review.
The Insurance Estimate Is Your Documentation Blueprint
Most insurance adjusters use a software platform called Xactimate to produce the scope of loss — a detailed, line-by-line estimate of what reconstruction work the policy covers. Every line item in that estimate carries a description, a unit of measurement, a quantity, and a price.
Your documentation system should treat the Xactimate estimate as the organizing backbone for everything that follows. Every invoice your contractor submits and every progress photo you capture should connect back to specific line items in that estimate. When the adjuster or loss-draft department reviews a draw request, they are checking whether the invoiced work matches what was approved and whether the photos confirm that the work was actually carried out.
Obtain a copy of the adjuster's estimate at the start of your project. If your contractor provides their own scope of work or bid, compare it against the insurance estimate so you understand where the two align and where there may be gaps that require supplemental claims or direct discussions with the carrier.
How to Build a Master Filing System for Draw Documentation
A well-organized filing system saves hours of searching, reduces errors in draw submissions, and makes it easier for your contractor, adjuster, and loss-draft department to process requests efficiently. Use a cloud-based digital folder system as the primary record, with physical backup copies stored in a separate location.
Recommended Folder Structure for a Fire Damage Rebuild
The folder structure below is tailored to fire damage reconstruction projects. Each folder corresponds to a category of documentation you will need throughout the rebuild:
- 01 – Insurance Estimate and Scope of Loss: The adjuster's Xactimate estimate, any supplements or revisions, and correspondence about scope changes.
- 02 – Permits and Plan Check Records: Building permits, approved plans, plan check comments, and permit inspection cards or records.
- 03 – Contractor Agreements and Change Orders: The signed construction contract, any executed change orders, and written correspondence about scope modifications.
- 04 – Draw Requests (numbered subfolders by draw): Each draw gets its own subfolder containing the draw cover sheet, invoices, photos, lien waivers, and proof of payment for that phase.
- 05 – Progress Photos – Master Archive: All project photos organized by date and phase, kept separate from the curated photo sets included in individual draw packets.
- 06 – Inspection Records: City or county inspection results, third-party inspection reports, and any loss-draft inspection documentation.
- 07 – Lien Waivers: Conditional and unconditional lien waivers from the general contractor, subcontractors, and material suppliers, organized by draw.
- 08 – ALE Documentation: Additional Living Expenses records, maintained completely separate from reconstruction draw documentation.
- 09 – Warranties and Closeout Documents: Manufacturer warranties, contractor warranty documentation, certificate of occupancy, and final handoff records.
Keep your ALE documentation in its own dedicated folder. ALE covers temporary housing and related living expenses while your home is being rebuilt. It is a separate line item from reconstruction funding, and mixing ALE records into your draw documentation creates confusion during reviews.
File Naming Convention
Use a consistent naming convention so any file can be identified without opening it. A practical format for fire damage rebuilds:
Draw-[number]_[date]_[phase]_[description].[extension]
Examples:
- Draw-03_2025-08-12_Framing_East-Elevation-Complete.jpg
- Draw-03_2025-08-14_Framing_Invoice-Martinez-Framing-LLC.pdf
- Draw-03_2025-08-14_Framing_Lien-Waiver-Conditional-Martinez.pdf
This convention identifies the draw number, date, construction phase, and file content at a glance. It also keeps files sorted chronologically within each folder.
How to Organize Progress Photos for Each Draw
Progress photos serve a defined purpose in the draw process: they provide visual evidence that the invoiced work was completed, that the work conforms to the approved scope, and that construction reached the milestone described in the draw request. Photos are not decorative — they function as verification tools.
What Photos to Take and When
For each construction phase, capture three categories of photos:
- Before the phase begins: Document the starting condition so the adjuster can see what existed before work was performed. In a fire rebuild, this may include cleared areas, exposed foundations, or rough framing before sheathing is applied.
- During active work: Capture work in progress, particularly work that will be concealed by subsequent phases. Structural framing connections, insulation placement, rough electrical and plumbing runs, waterproofing installations, and shear panel nailing patterns should all be photographed before they are hidden behind drywall or finish materials.
- After phase completion: Document the finished condition of the phase, showing the scope of work that corresponds to the draw request.
The most critical photos for insurance draws are those taken before work is covered up. Once drywall is in place, there is no way to visually verify what lies behind it. This is especially relevant in wildfire rebuilds where structural repairs, insulation upgrades, rough MEP systems, and waterproofing details are all concealed during later phases.
What Each Photo Should Show
For each area or scope item, follow a wide-to-close approach:
- Wide shot: Shows the full room, wall section, or area being documented. Establishes location and scale.
- Medium shot: Shows the specific work area in context — the framed wall, the installed window, the rough plumbing layout.
- Close-up: Shows detail relevant to verification — fastener patterns, connection hardware, material label data, inspection tags.
The adjuster reviewing a draw request is using photos to confirm that the described work was performed and that the scope matches what was approved. Wide shots without close-ups leave room for questions. Close-ups without wide shots lack context. Providing both gives reviewers what they need to process the draw without follow-up requests.
How to Label and Store Progress Photos
Apply the file naming convention described above to every photo. Make sure your camera or phone has timestamps enabled, and confirm that location metadata is active if your device supports it. Timestamps and geotags provide independent verification that a photo was taken at the project site on the date claimed.
For each draw, create a photo log — a straightforward document that pairs each photo with a brief description and the corresponding invoice line item or Xactimate line item it documents. A simple table with three columns works well:
- Photo file name
- Description of what the photo shows
- Corresponding estimate or invoice line item
This photo log becomes part of your draw packet. It allows the adjuster or loss-draft reviewer to connect your photos to your invoices without having to guess at the relationship between them.
How Many Photos Are Enough
No universal number applies to every project or every carrier. The appropriate amount depends on the scope of work in each phase, the number of rooms or areas involved, and the complexity of what is being documented.
A useful benchmark: if you had to walk someone through the completed work without them ever visiting the site, would your photos give them a clear picture? If not, take more. For fire damage rebuilds — where the scope is often extensive and involves multiple trades working across the entire property — thorough coverage is the right approach.
Some insurance carriers or loss-draft departments have specific photo requirements. Check with your carrier or ask your contractor whether the adjuster has communicated any documentation expectations particular to your project.
How to Organize Invoices for Each Draw
Matching Invoices to the Insurance Estimate
Each invoice submitted as part of a draw request should reference the corresponding work described in the insurance estimate. If the Xactimate estimate includes a line item for roof sheathing removal and replacement covering a specific quantity, the invoice from the roofing subcontractor should describe the same scope in compatible terms.
This does not mean the invoice has to use exact Xactimate language or line-item codes. It means the scope, quantity, and description on the invoice should be clear enough that the reviewer can connect it to the estimate without extensive interpretation.
Vague invoices — those that bundle large amounts of work into a single dollar figure with minimal description — create friction in the review process. Invoices that are specific about scope, location, quantities, and rates are easier to review and move through approval more efficiently. When your contractor submits invoices, request enough detail that each line of work can be traced back to the approved estimate.
Separating Materials and Labor
Many insurance estimates break costs into materials and labor as separate line items. When possible, invoices should reflect the same structure. If your contractor's invoices combine materials and labor into a single figure, the adjuster may request a breakdown before approving the draw. Asking for separated invoices at the outset avoids that back-and-forth.
Proof of Payment and Receipts
A draw request often requires proof that the contractor or subcontractor was actually paid for the work — not simply that an invoice was issued. Acceptable proof of payment typically includes:
- Copies of canceled checks (front and back)
- Wire transfer confirmations
- Credit card receipts or statements showing the charge
- Bank statements confirming the payment cleared
Loss-draft departments in particular may require proof of payment before releasing the next draw. This protects the lender's interest by confirming that funds from the previous draw were directed to the project. Store proof of payment documents in each draw's subfolder alongside the corresponding invoices.
Handling Change Orders
A change order documents any modification to the original scope of work — additions, deletions, or revisions that were not part of the initial contract or insurance estimate. Change orders are common in fire damage rebuilds, where concealed damage is frequently discovered during demolition or framing.
Maintain change orders in a dedicated section of your master filing system, and reference them explicitly in the draw packet whenever a draw includes change-order work. Invoicing for work that falls outside the original scope without a corresponding executed change order is one of the most common sources of draw disputes. If the invoiced amount exceeds what the estimate covers for a given phase and no change order explains the difference, the draw will likely be questioned or held in part.
When additional damage is discovered during reconstruction and the scope needs to expand, this typically requires a supplemental claim with the insurance carrier. Documentation for supplemental claims — including photos of the newly discovered damage, a revised estimate, and written communication with the adjuster — should be filed separately from standard draw documentation but cross-referenced in the relevant draw packet.
Lien Waivers: What They Are and Why They Matter for Draw Release
A lien waiver is a document signed by a contractor, subcontractor, or material supplier confirming that they have been paid for the work described and waive their right to file a mechanic's lien against your property for that amount. Lien waivers protect you as the homeowner by establishing that the people who worked on your property have been compensated.
Insurance carriers and loss-draft departments typically require lien waivers as part of draw packets because they reduce the risk that unpaid workers or suppliers will place a lien on the property after funds have been released.
Conditional vs. Unconditional Lien Waivers
There are two types, and the timing of each matters:
- Conditional lien waiver: Signed at the time of the draw request, stating that the contractor waives their lien rights on the condition that payment is actually received. This is submitted with the draw request, before funds are released.
- Unconditional lien waiver: Signed after payment has been received and cleared, confirming that the contractor has been paid and unconditionally waives lien rights for that amount. This is typically collected after each draw is funded and submitted with the following draw request as confirmation that the prior draw was settled.
Collect conditional lien waivers from the general contractor and any subcontractors or material suppliers involved in the current draw. Collect unconditional lien waivers once payment has cleared. File both types in the Lien Waivers folder and include copies in the relevant draw subfolder.
Missing lien waivers are a frequent cause of draw holds. A loss-draft department that does not receive the required waivers may delay or partially release funds until the documents are provided. Building a routine for collecting lien waivers with each draw — rather than attempting to gather them after the fact — prevents this problem from recurring.
How to Assemble a Complete Draw Packet
A draw packet is the complete submission you or your contractor provides to the insurance carrier or loss-draft department to request the release of funds for a completed phase of work. A well-assembled draw packet gives the reviewer everything needed to understand what work was done, verify that it matches the approved scope, confirm that invoices are supported by documentation, and release funds without requesting additional information.
What a Draw Packet Should Contain
For each draw, compile the following into a single, clearly labeled package — ideally as one organized PDF:
- Draw cover sheet: A summary page identifying the draw number, the construction phase covered, the total amount requested, a brief description of the completed work, and the submission date. This gives the reviewer a clear overview before they examine the supporting documents.
- Invoices: Itemized invoices from the general contractor and any subcontractors for the phase, matched to insurance estimate line items where possible.
- Proof of payment: Documentation confirming that prior draw funds were applied to the project, if required by the loss-draft department.
- Photo report: A curated set of progress photos for the phase, organized with the photo log that connects each image to the corresponding scope item.
- Inspection records: Copies of passed inspection reports from the building department for the phase, if applicable. Many carriers and loss-draft departments will not release certain draws until specific inspections have been passed and documented.
- Conditional lien waivers: From the general contractor and all subcontractors or suppliers involved in the current draw.
- Unconditional lien waivers: From the previous draw, confirming that those funds were received.
- Change order documentation: If the draw includes work outside the original scope, include the executed change order and any supplemental claim correspondence.
Label each section clearly within the PDF. A reviewer who can locate what they need quickly is more likely to process the draw without generating follow-up requests.
The Connection Between Permit Inspections and Draw Timing
In California, most fire damage rebuilds require multiple permit inspections at defined construction milestones — foundation, framing, rough electrical, rough plumbing, rough mechanical, insulation, drywall, and final inspection, among others. These inspections confirm that work meets applicable building codes.
Many insurance carriers and loss-draft departments treat passed inspections as documentation anchors for draw releases. A framing draw, for example, may not be approved until the framing inspection has been passed and the inspection record is included in the draw packet.
Inspection timing therefore directly affects draw timing. If an inspection is delayed — due to scheduling, required corrections, or building department workload — the corresponding draw may be delayed as well. Understanding this relationship helps you plan documentation submissions and set realistic expectations for when funds will be available.
Your building department, contractor, and insurance carrier can each provide guidance on inspection requirements specific to your project. Requirements may vary based on scope, location, and the authority having jurisdiction.
A Master Draw Log to Track the Full Project
Beyond organizing each draw's documentation individually, maintain a master draw log that tracks the full project across all draws. This is a single document — a spreadsheet or table — that records:
- Draw number
- Date submitted
- Construction phase covered
- Amount requested
- Amount approved and released
- Date funds received
- Any notes about holds, partial releases, or follow-up requests
This log gives you a clear view of the project's financial status at any point during the rebuild. It also helps identify patterns — if draws are consistently being partially released or held, the log can help you pinpoint where documentation gaps are occurring and address them before the next submission.
Common Documentation Mistakes That Delay Insurance Draws
Given the complexity of fire damage rebuilds and the documentation requirements involved, the following mistakes most frequently cause draw delays:
- Invoices that do not match the insurance estimate: Vague descriptions, bundled line items, or amounts that do not correspond to approved scope items trigger review holds.
- Missing lien waivers: A draw packet submitted without conditional lien waivers — or without unconditional lien waivers from the previous draw — is often held until the documents arrive.
- Photos without timestamps or location context: Photos that cannot be independently verified as taken at the project site on the claimed date may not satisfy the reviewer.
- Photos that do not show the work claimed: Images that look substantially the same as the previous draw's photos, or that do not clearly show the scope of completed work, raise questions that slow the review.
- Undocumented change orders: Invoicing for work that falls outside the original scope without an executed change order and supplemental claim documentation creates disputes.
- Incomplete proof of payment: Loss-draft departments that require proof of payment before releasing the next draw will hold funds until that documentation is provided.
- Mixing ALE and reconstruction documentation: Including temporary housing receipts or ALE records in a reconstruction draw packet creates confusion during review and can delay both categories of reimbursement.
- Missing inspection records: Submitting a draw for a phase that requires a passed inspection without including the inspection documentation may result in a hold until the record is provided.
- Disorganized draw packets: A packet that requires the reviewer to search for documents, match unlabeled photos to invoices, or piece together scope from scattered records takes longer to process and is more likely to generate follow-up requests.
Who Submits the Draw — and What the Homeowner's Role Looks Like
The answer depends on your contract with your contractor and the specific requirements of your insurance carrier and loss-draft department. In some arrangements, the contractor assembles and submits draw packets directly. In others, the homeowner submits the draw request with supporting documentation provided by the contractor. In many fire damage rebuilds, the process is collaborative — the contractor produces the documentation, and the homeowner reviews, signs, and submits it.
Regardless of who handles submission, you as the homeowner should:
- Maintain your own copy of every draw packet submitted
- Review invoices against the insurance estimate before each draw is submitted
- Confirm that lien waivers are collected at each phase
- Track draw amounts and release dates in the master draw log
- Communicate directly with the loss-draft department if you have a mortgage, so you understand their specific requirements and timelines
Before signing a construction contract, ask your contractor how they manage draw documentation and what role you will play in that process. Understanding the documentation workflow is an important part of evaluating any potential rebuild partner.
How 1st Choice Development Approaches Draw Documentation
At 1st Choice Development, documentation is built into the rebuild process from the start — not assembled as an afterthought at the end of each phase. For homeowners in Altadena and Pacific Palisades rebuilding after wildfire damage, we treat draw documentation as an integral part of the controlled construction operation that defines how we manage every project.
Our project control system tracks each construction phase from initial site setup through final inspection and owner orientation. At each milestone, jobsite documentation — including progress photos, inspection records, and schedule updates — is produced as part of normal field operations, not as a separate task competing for attention during active construction.
That documentation supports the draw process by providing organized, phase-specific records that connect to the approved scope. Our field management team coordinates with subcontractors to collect lien waivers, maintain photo logs, and prepare draw packet materials so that submissions are complete before they reach the carrier or loss-draft department.
We cannot guarantee draw approval timelines, insurance decisions, or loss-draft release schedules — those are determined by the carrier, the lender, and the specific requirements of each policy and project. What we can do is manage the documentation process so that the records we produce are organized, thorough, and ready for review when each phase is complete.
If you are rebuilding after fire damage and want to understand how draw documentation fits into the broader reconstruction process, schedule a rebuild consultation with 1st Choice Development to discuss your project.
Frequently Asked Questions
What is the difference between an insurance draw and a reimbursement?
An insurance draw is a partial release of funds from your insurance claim proceeds, authorized in stages as construction phases are completed and documented. A reimbursement implies that you paid out of pocket first and are seeking repayment after the fact. In most fire damage rebuilds with active insurance claims, the process follows the draw model, where funds are released incrementally as work progresses.
Do I need lien waivers for every draw?
Most insurance carriers and loss-draft departments require lien waivers with each draw request. Conditional lien waivers are submitted with the current draw. Unconditional lien waivers from the previous draw are submitted as confirmation that those funds were received by the contractor and subcontractors. Check with your carrier and loss-draft department for their specific requirements.
Can I use my phone to take progress photos for insurance draws?
Yes. A smartphone camera is generally acceptable for draw documentation photos, provided the images are clear, well-lit, and include timestamps and location metadata. What the photo actually shows — and how it is labeled and organized — matters more than the type of camera used to capture it.
What happens if I submit incomplete documentation?
The carrier or loss-draft department will typically hold the draw or issue a partial release while requesting the missing documents. This delays funding and can create cash-flow pressure on the project. Submitting complete, well-organized draw packets from the start avoids that cycle.
How does the mortgage servicer's loss-draft department affect my draw?
If you carry a mortgage on the property, your insurance claim check is often sent to the mortgage servicer rather than directly to you. The servicer's loss-draft department holds those funds and releases them in draws based on their own review process, which may include third-party inspections. This introduces a layer of documentation and timing requirements beyond what the insurance carrier alone requires. Contact your mortgage servicer early in the rebuild to understand their loss-draft process and documentation expectations.
Should I keep physical copies or is digital storage enough?
A cloud-based digital system is the primary recommendation because it allows organized access, straightforward sharing, and reliable backup. That said, keeping a physical binder with printed copies of key documents — the insurance estimate, the contract, each draw cover sheet, and lien waivers — provides a secondary backup and can be useful during in-person meetings with the adjuster, contractor, or loss-draft inspector.
What if my contractor's invoice does not match the insurance estimate exactly?
Minor differences in terminology between a contractor's invoice and the Xactimate estimate are normal and generally not a problem. The key is that the scope, quantity, and intent are clearly aligned. If there is a meaningful discrepancy — the invoice covers work not included in the estimate, or the amount exceeds what was approved for that phase — address it before submission through a change order, supplemental claim, or direct communication with the adjuster. Submitting a draw with unexplained discrepancies invites delays and additional review.
Start With a Clear Documentation System and Build From There
Organizing progress photos and invoices for insurance draws is straightforward in concept, but it requires consistency and attention across many months of active construction. For homeowners in Altadena and Pacific Palisades managing a wildfire rebuild, the draw documentation process touches every phase of the project — from the first site clearing through final inspection and handoff.
The most important step is to establish your filing system and naming conventions before construction begins, align your documentation to the insurance estimate from day one, and treat draw documentation as an ongoing part of the rebuild — not something to assemble under deadline pressure after the fact.
If you are preparing for a fire damage rebuild and want to work with a contractor who manages documentation as part of the construction process, schedule a rebuild consultation with 1st Choice Development to discuss your project and learn how our approach to project documentation supports the draw process from start to finish.
Questions about your rebuild?
We rebuild fire-damaged homes across Altadena and Pacific Palisades, and we are happy to talk through your situation.
Talk to us